eBridge Fund, powered by BCIC

Business loans from $15,000 to $50,000

The eBridge Fund lends to small businesses in Cameron County, with fixed rates from 5%, never above 10%, and up to 7 years to repay.

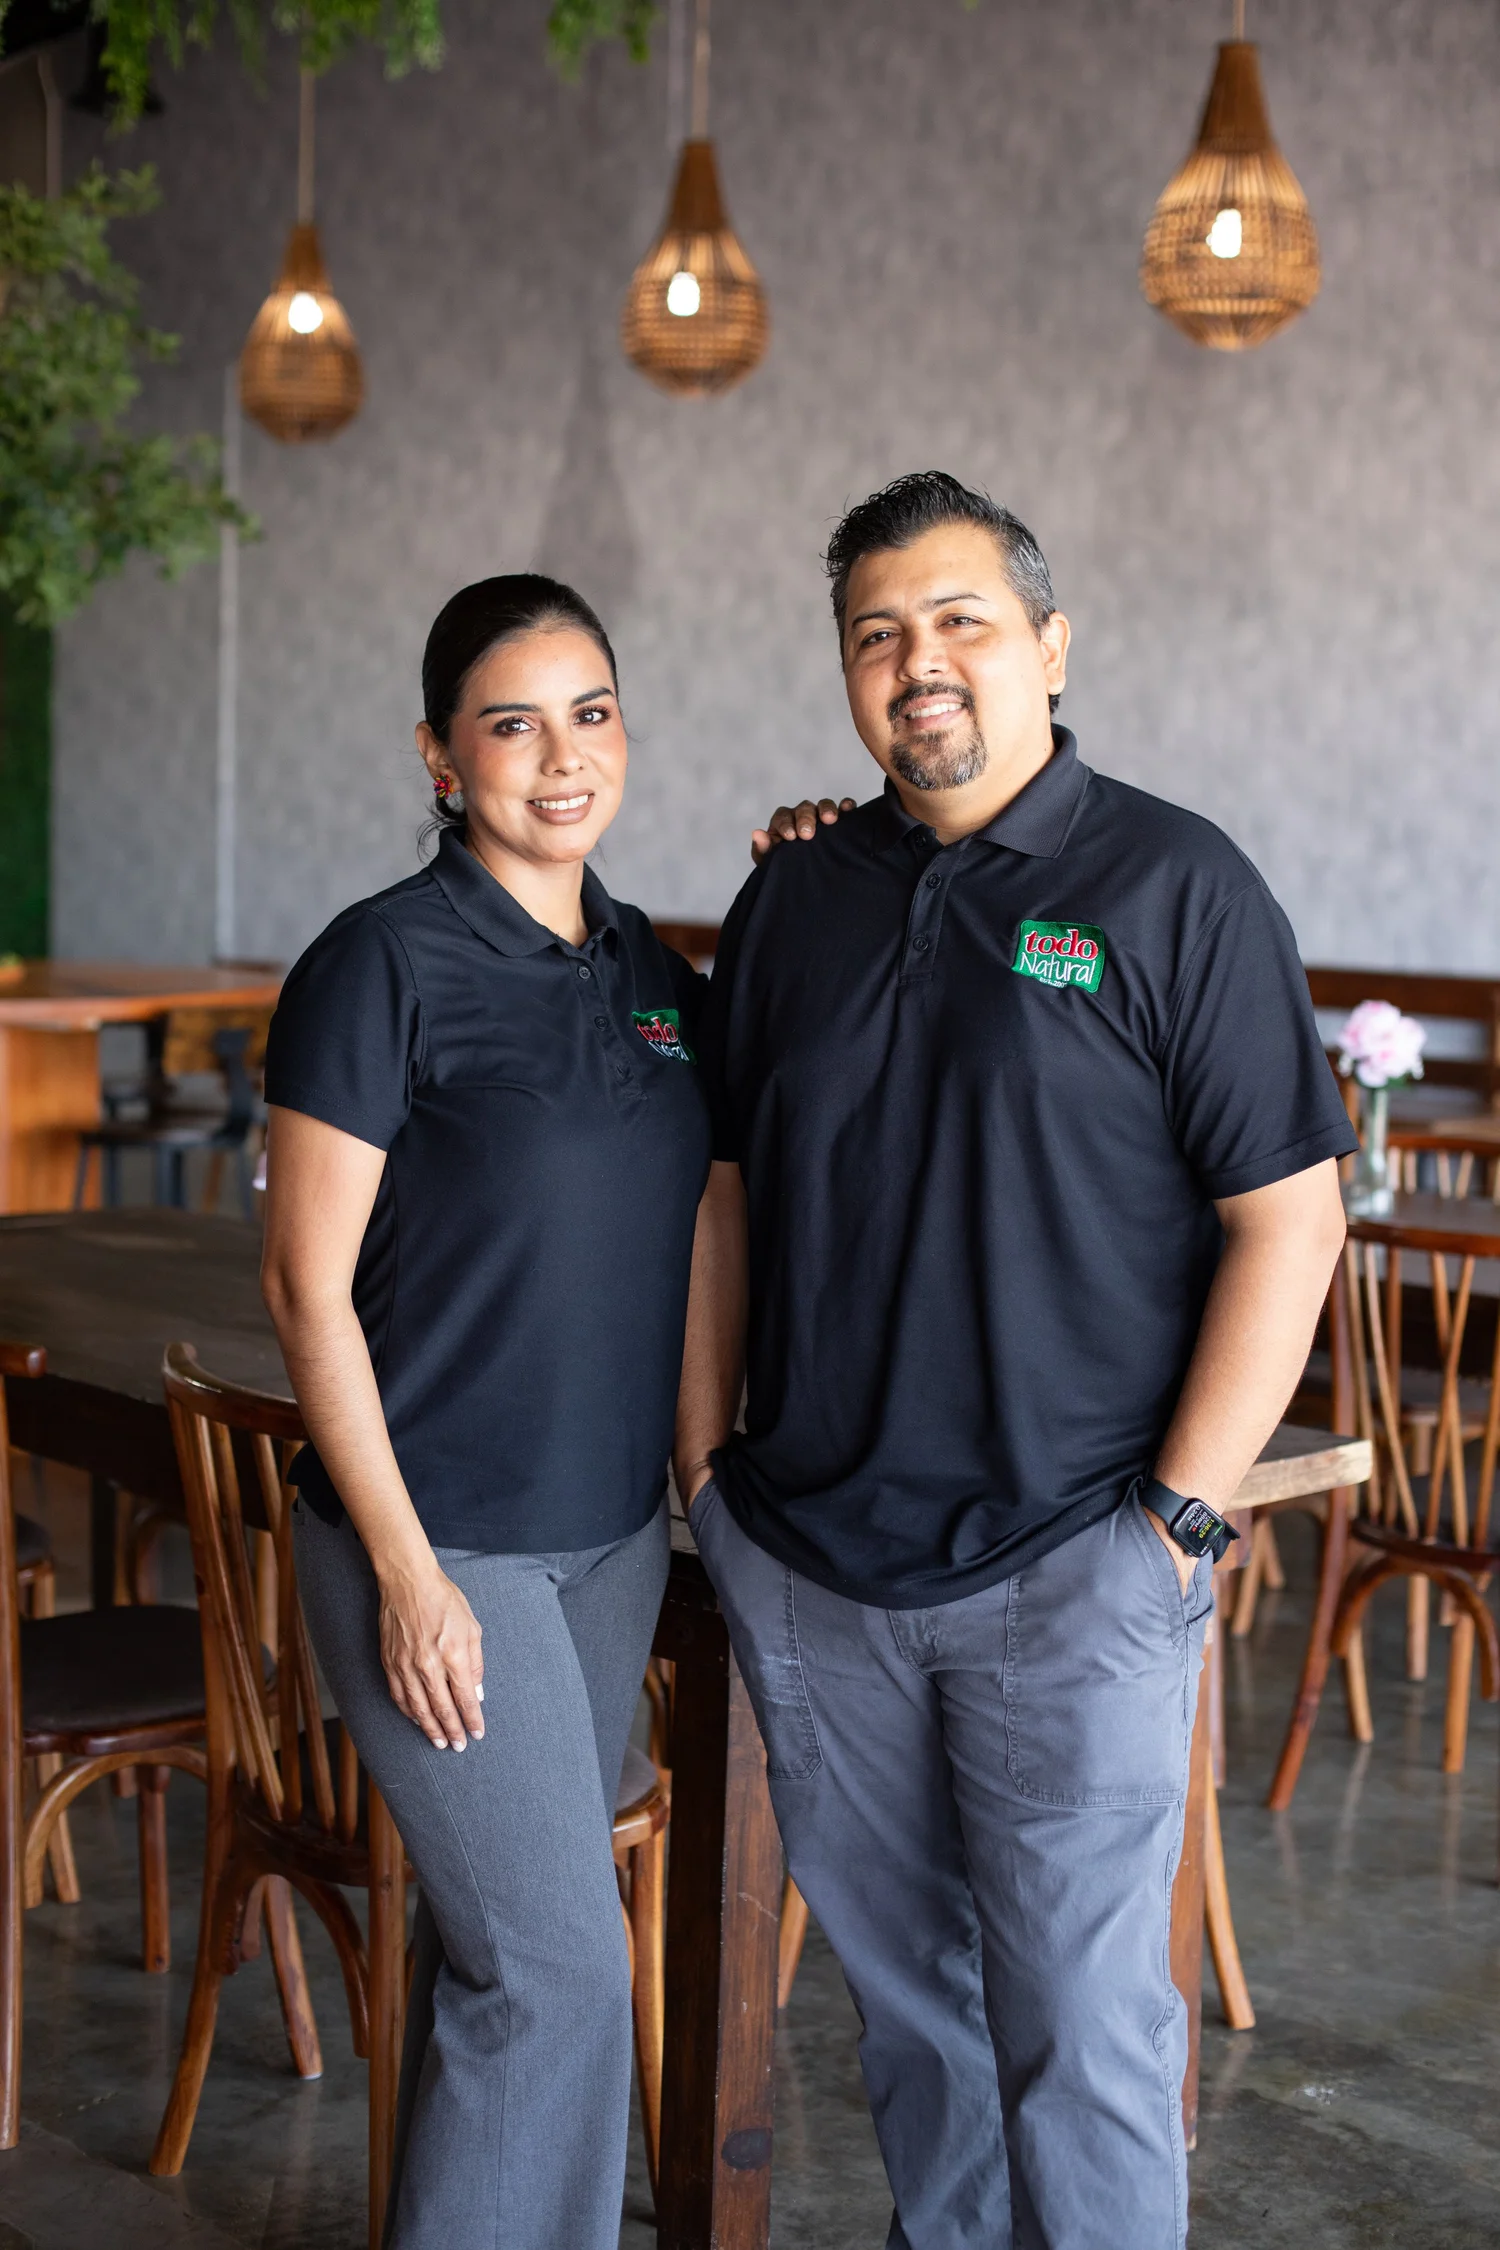
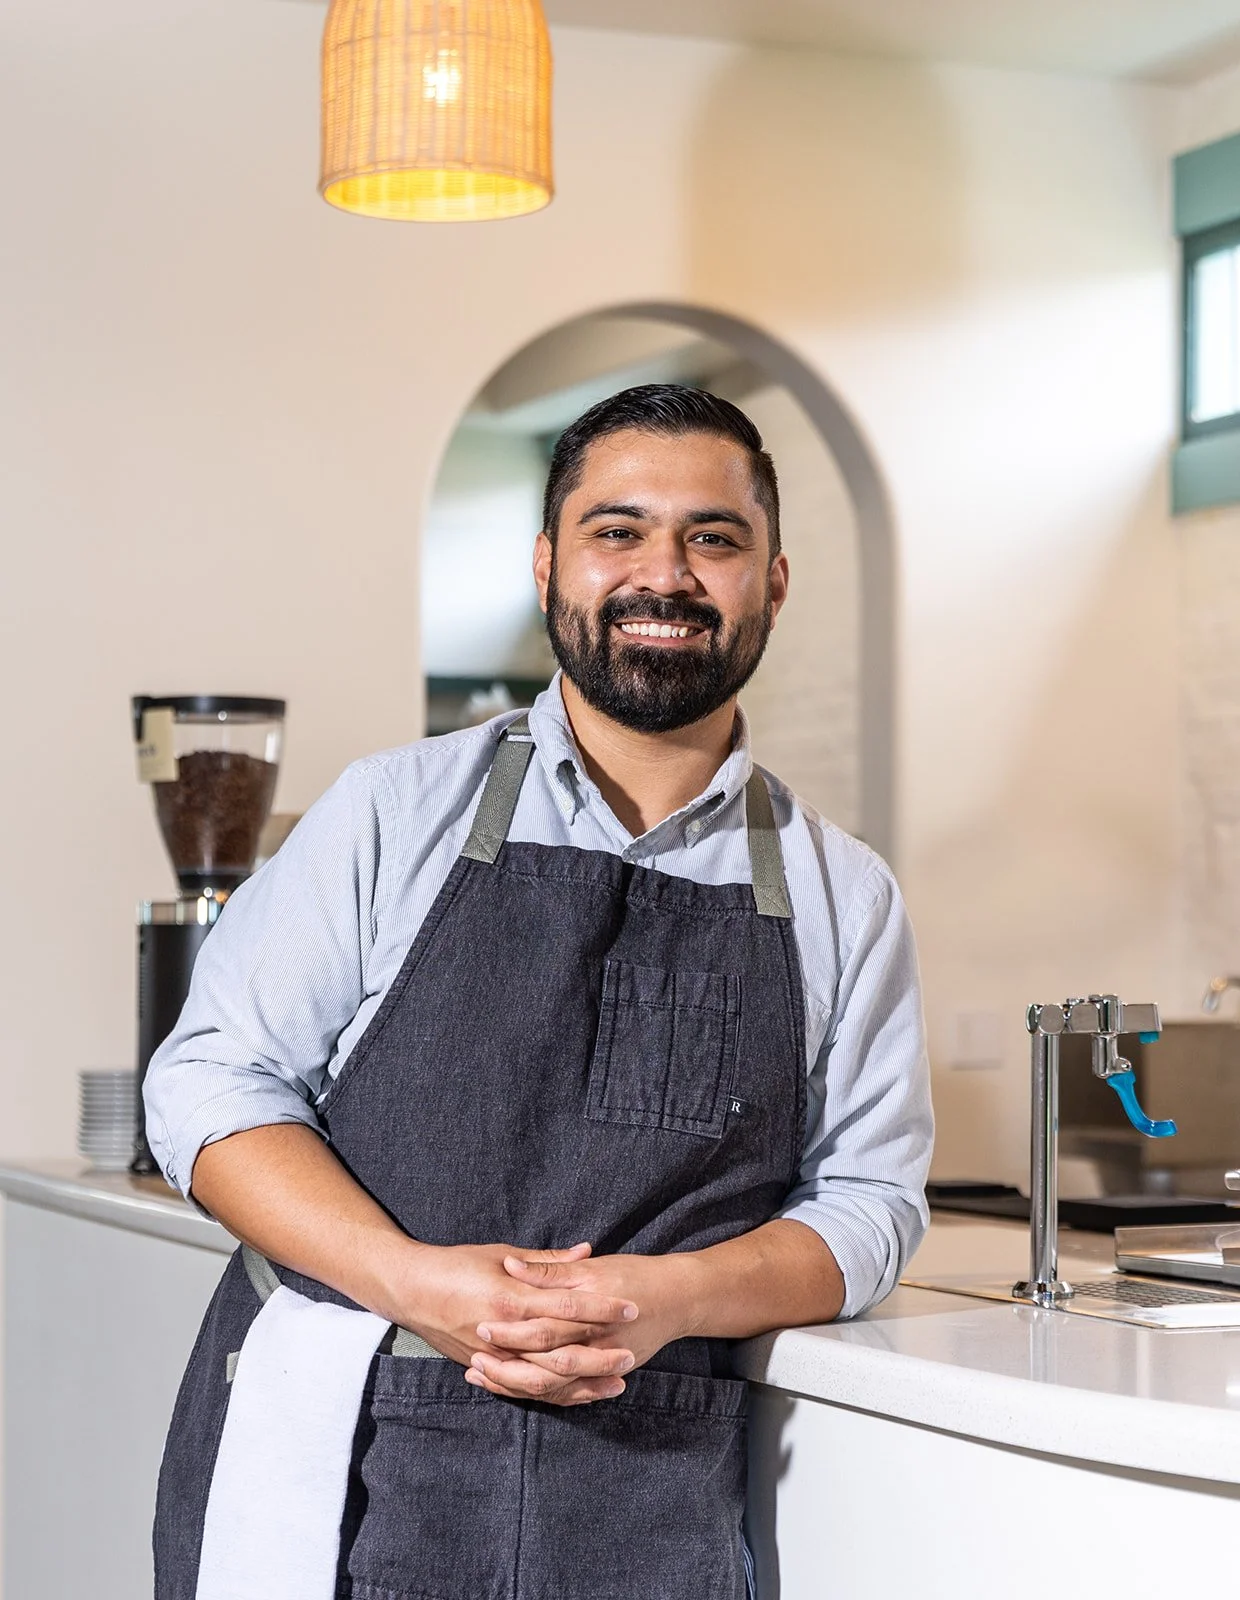
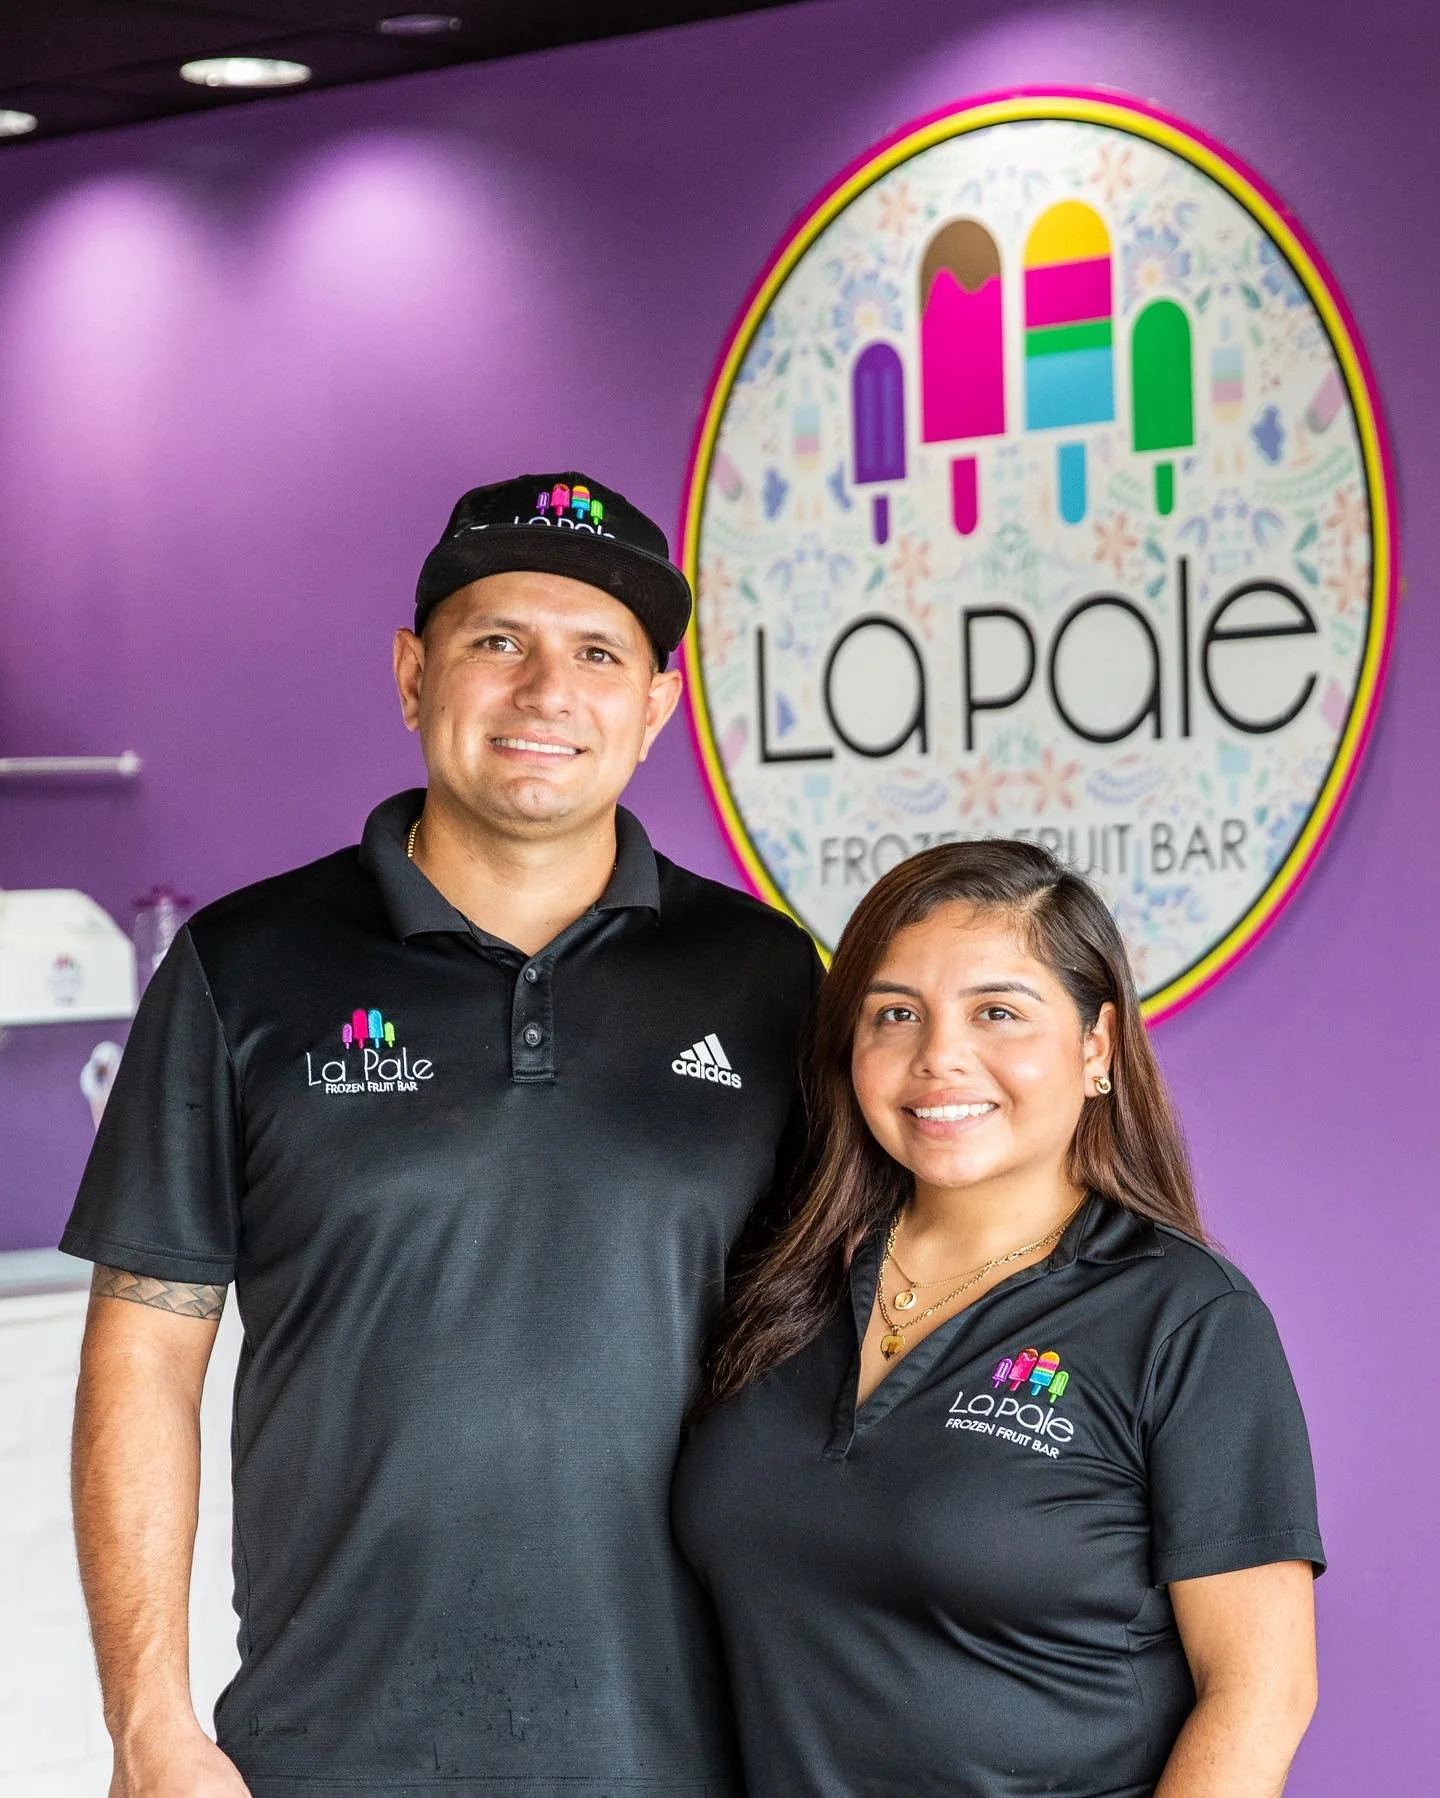
Cristina Guillen and Cristina Muñoz, owners of Cero Grados Francisco Gonzalez and Eva Marlene Moreno, owners of Todo Natural Omar Garza, owner of Warbler Coffee The La Pale Frozen Fruit Bar team in front of their sign The Pluton Brewing Co. team toasting at the bar The Chilmoli Mexican Steakhouse team The Las Ramblas Hospitality Group team at the bar

Cero Grados

Todo Natural

Warbler Coffee

La Pale Frozen Fruit Bar

Pluton Brewing Co.

Chilmoli Mexican Steakhouse

Las Ramblas Hospitality Group

$15K–$50K

loan amounts

5%–10%

fixed interest rate

7 years

longest repayment term

$50

application fee, may be waived

Rates last updated November 13, 2026.

Start here

The application is online. You'll create an account with your email and upload every document in the portal.

0–3 years in business

Startups

Up to $25,000

3+ years in business

Existing businesses

Up to $50,000

Have these ready before you apply

  • Proof that you have 10–15% of the project cost available; savings count
  • A 10% down payment
  • Collateral: business assets such as equipment, inventory or receivables, or personal property
  • Your financial documents, and a brick-and-mortar location in Cameron County

Document checklist (PDF) · Loan guidelines 2026 (PDF)

$20,000
$15k$25k
5 years
5.06%

$0

How the eBridge Fund rate compares

Interest rates from typical small-business lenders, side by side. Lower is better.

5.25% fixed eBridge Fund rate today 75% of the Wall Street Journal Prime Rate, never below 5% or above 10%. Set at loan approval.
10% rate cap
    About these figures

    Prime rate 7% (Wall Street Journal, September 2026). Comparison ranges checked July 2026.

    Figures are estimates for comparison only, not offers. The bank range is based on national small-business bank loan rates (Federal Reserve survey data); local rates vary and aren't published. Actual rates vary by borrower, lender, term, and credit. SBA figures are program maximums. Some online and alternative lenders charge well above this range. eBridge Fund loans serve commercial, brick-and-mortar businesses in Cameron County; terms and eligibility are on this page.

    How the loan works

    Check that you qualify

    Read the program guidelines to confirm your project fits: a Cameron County location, new jobs, 10–15% of the project cost available, and local land-use and permit rules.

    About 10–30 minutes

    Pre-apply online

    Create an account in the loan portal and fill out the pre-application. If it's approved, pay the $50 application fee to hold your spot in the monthly review. The fee may be waived.

    20–45 minutes. We reply in 5–7 business days.

    Send your full application

    Upload your documents using the checklist. Need help with records or a business plan? We'll connect you with SCORE, SBDC, UTRGV ECC or the Brownsville Chamber.

    1–3 days if your documents are ready, 1–2 weeks if not

    Review and Board approval

    Staff reviews your file, asks questions if needed and prepares a recommendation. The Board considers it at its next monthly meeting.

    60–90 days in all

    Rules, terms and details

    Open any section for the full details.

    Who can apply

    Cameron County businesses with a physical location

    • Startups (0–3 years) and existing businesses (3+ years) with a commercial, brick-and-mortar location in Cameron County.
    • Your business creates new jobs with competitive wages.
    • You can show creditworthiness and the ability to repay the loan.
    • You submit the required financial and supporting documents.
    • The project follows city and county land-use plans and rules.
    • Who can't borrow: BCIC Board and Loan Committee members, BCIC staff, City Commissioners and their immediate families. A waiting period applies after they leave their role. Tell us about any of these relationships when you apply.

    What you can use it for

    Working capital, property, equipment and more

    • Working capital
    • Buying commercial land or buildings for your business
    • Site preparation, construction, rehabilitation or leasehold improvements
    • Equipment, machinery and fixtures, including installation
    • Targeted public infrastructure tied to your business
    • Not covered: residential construction or speculative housing, real estate investment that isn't tied to an operating business, refinancing existing debt, and prohibited industries such as gambling or adult entertainment.

    Rates, terms and fees

    Fixed rates from 5%, never above 10%, up to 7 years

    • Interest: fixed for the life of the loan. Rates start at 5% and are never above 10%. They're based on the Wall Street Journal prime rate (75% of prime), and your rate is set when the loan is approved. Rates last updated November 13, 2026.
    • Loan size: from $15,000, up to $25,000 for startups (0–3 years) and up to $50,000 for existing businesses (3+ years).
    • Term: up to 7 years.
    • Origination fee: 3% of the loan, paid at closing. It can be financed on loans above $25,000.
    • Application fee: $50, non-refundable, may be waived depending on your profile. Pay in the portal, or by check or money order to Brownsville Community Improvement Corporation.
    • Down payment: at least 10% of the project.
    • Paying early: no prepayment penalty.
    • Funding is limited, and applications are considered as funds allow.

    Collateral and your own capital

    What backs the loan

    Every loan needs collateral; the type and amount depend on the risk. Business assets such as inventory, machinery, equipment, fixtures and receivables count. If they aren't enough, personal assets may be needed.

    Owners with 20% or more of the business sign a personal guarantee: if the business can't repay, the guarantors are personally responsible for the loan.

    The loan won't pay for the whole project. Show that you have 10–15% of the project cost available; the exact share is set during review.

    How we review your application

    Character, capacity and conditions

    • Character: are the owners committed and qualified to run the business?
    • Capacity: is the business plan viable, and can the borrower repay the loan and other bills?
    • Conditions: do the terms meet the business's needs?
    • Review starts once the $50 fee is paid (or waived) and every required document is in the portal. Staff underwrites the loan and takes it to the Loan Committee. If the committee supports it, we share the proposed terms with you. Once you accept them, the Board of Directors considers the loan at its next meeting.
    • Funds usually go out 15–30 days after Board approval and closing.
    • Common reasons for denial: missing documents, not enough equity or collateral, unresolved bankruptcies, speculative projects, or not showing job creation or the ability to repay.

    After your loan closes

    Payments, reports and support

    • Your repayment schedule is set at closing, based on the loan amount, the term and your cash-flow projections.
    • We stay involved: borrowers send annual financial statements and job reports every six months until the loan is repaid, and we visit the project from time to time.
    • The loan agreement lists any other conditions, such as telling us about major changes to your operations or ownership.
    • We can also connect you with technical assistance.

    Guidelines and documents

    Program rules and the document checklist

    Common questions

    Short answers to what people ask us most.

    What is the eBridge Fund?

    A local, revolving loan fund that makes low-interest, fixed-rate loans to commercial, brick-and-mortar businesses in Cameron County. Because it revolves, your repayments go back into the fund and are lent to the next entrepreneur.

    Who runs the program?

    The Brownsville Community Improvement Corporation (BCIC) runs the eBridge Fund. Its Loan Committee and Board of Directors make the final lending decisions.

    Why choose the eBridge Fund instead of a bank?

    It's built for businesses that need more flexible, local underwriting than banks usually offer, or a more competitive rate. We look at community impact, job creation and how ready your project is, and we keep supporting you after the loan closes.

    When does my application get reviewed?

    Once the $50 application fee is paid (or waived) and the portal has every required document. Missing documents delay the review.

    How long does it take?

    Usually 60–90 days from a complete application to a final decision, depending on how complete it is and when the next Board meeting falls. Funds go out after Board approval, once documents, insurance and other closing conditions are done.

    Can I pay my loan off early?

    Yes. There's no prepayment penalty.

    What if I have trouble making my payments?

    Contact us right away. Talking early lets us look at options such as a temporary change or a workout plan; waiting only makes things harder. Your loan agreement explains what happens in a default.

    Can my application be denied?

    Yes. The most common reasons are missing documents, not enough equity or collateral, unresolved bankruptcies, speculative projects, or not showing job creation or the ability to repay. A conflict of interest or an ineligible industry can also disqualify an application.

    Questions? Talk to a person

    The loan team can walk you through the application before you start.

    Anthony Cantu

    Anthony Cantu

    Small Business Lending Coordinator

    acantu@brownsvillecic.com
    (956) 561-1766

    Victoria Padron

    Victoria Padron

    Chief Operating Officer and Finance Program Director

    vpadron@brownsvillecic.com
    (956) 551-2494

    Book a meeting

    Pick a time below to speak with Anthony Cantu about your eBridge Fund application.

    Contact us

    Funding that grows with you

    We've worked with local businesses across Cameron County: entrepreneurs who needed an attainable path to capital, then used it to renovate spaces, buy equipment and hire local workers.

    Cristina Guillen and Cristina Muñoz, owners of Cero Grados

    “Our experience with the eBridge Fund has been excellent. The process was quick and simple because they walked us through every step.”

    Cristina Guillen & Cristina Muñoz
    Owners, Cero Grados

    Francisco Gonzalez and Eva Marlene Moreno, owners of Todo Natural

    “The funding from the eBridge Fund came as a blessing to our business.”

    Francisco Gonzalez & Eva Marlene Moreno
    Owners, Todo Natural

    Omar Garza, owner of Warbler Coffee

    “Every step you take to establish your business strengthens your confidence and ability to commit to a loan, making it a more calculated and strategic decision.”

    Omar Garza
    Owner, Warbler Coffee
    Success stories

    Have questions about the eBridge Fund?

    Fixed-rate loans of $15,000 to $50,000 for Cameron County businesses, never above 10% interest. Book a quick call to see if you qualify.